For Founders & Business Owners

Estate Planning for Founders and Business Owners

When a business becomes one of your largest assets, a standard estate plan can leave important questions unanswered. Ownership, personal guarantees, incapacity, succession, taxes, and family responsibilities begin to overlap. Cardon Law helps founders and business owners coordinate those moving parts so the plan can protect what they have built and give the people who may one day step in a clear path forward.

Schedule a Consultation
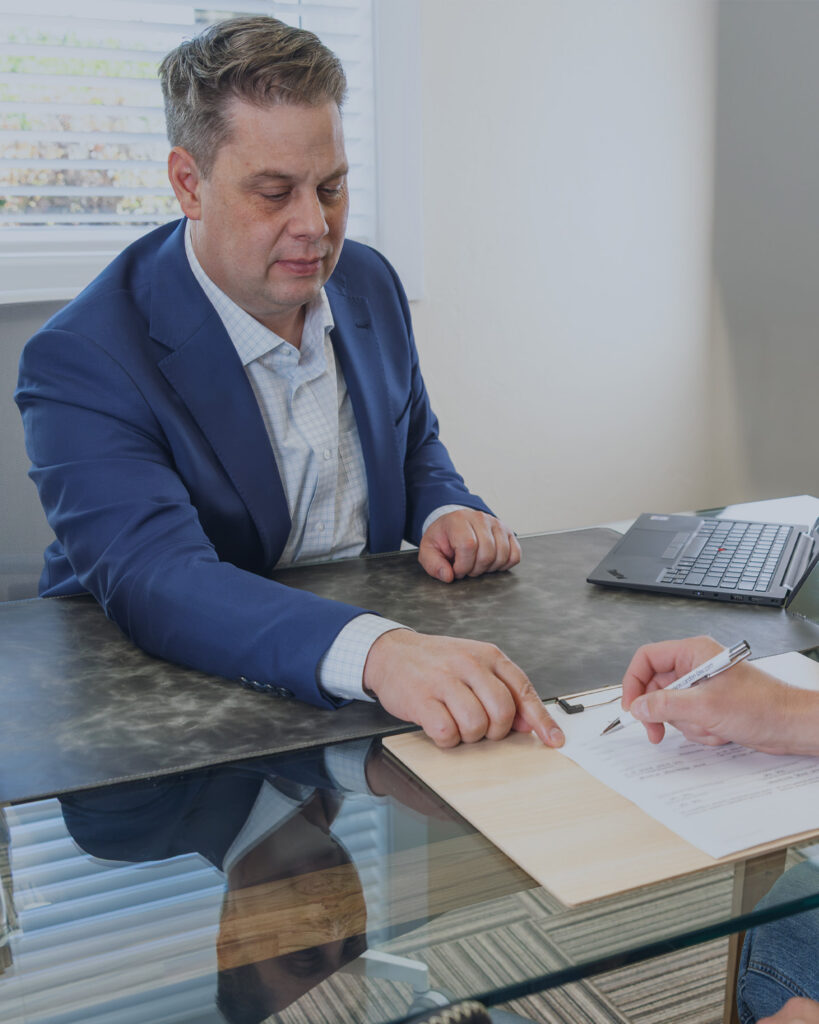
Founder reviewing business ownership and estate planning documents in an office

Your Estate Plan Should Evolve With the Business

Early in your company’s life, you may need a clear estate plan, incapacity documents, and a revocable trust. Those tools establish who can act and what happens if you die, but they do not address every risk a growing company creates.

As your business adds employees, debt, leases, investors, real estate, and value, your personal and business lives become more closely connected. Insurance and LLCs may handle part of the risk, while personal guarantees, ownership inconsistencies, or an approaching sale can introduce issues those tools do not solve.

The plan should be reviewed as your business changes. A structure that fit the company at launch may not fit it five years later, when you have accumulated personal wealth or begin preparing for succession or a liquidity event. The goal is to keep your estate plan aligned with the current business, the family, and the decisions that may come next.

Your business changes. The planning should change with it.
Why Business Ownership Changes the Planning

A business adds risks, authority questions, and ownership decisions that do not exist in the same way for every family. These four realities shape the planning analysis.

Business Risk Can Reach Your Personal Life

Growth often brings larger leases, debt, employees, contractual obligations, and personal guarantees. A claim or failed obligation inside the business can sometimes threaten assets outside it, especially when the owner has accepted personal liability or the ownership structure does not work as expected.

Ownership Becomes More Complex

Founders often add entities, real estate, investments, trusts, and agreements one decision at a time. The owner may remember why each piece exists even when the overall structure is difficult for a spouse, trustee, partner, or successor to understand.

Incapacity Affects the Business Too

If the owner cannot act, someone may need authority over more than household finances. Business interests, voting rights, entity management, contracts, and relationships with partners or advisors may continue to require decisions while the owner is unavailable.

Business Value Creates Future Decisions

As company value increases, the owner must consider whether the business will be retained, sold, transferred, or continued by someone else. A sale or other liquidity event can also create planning opportunities that depend on decisions made before the transaction is complete.

Planning That Grows With the Business

The right plan reflects the company’s current stage, the owner’s exposure, and the decisions that need attention next.

  1. Build the Foundational Estate Plan

    Business owners still need the core planning every family relies on: clear incapacity authority, a plan for death, a revocable trust when appropriate, and instructions for the people who may need to step in. Those documents create the foundation for every later layer of planning.

  2. Protect Personal Wealth From Business Risk

    As the business takes on larger obligations, planning should examine whether valuable personal assets are unnecessarily exposed. Insurance and entities remain important, but personal guarantees, direct liability, exclusions, and risks outside the company may require an additional layer of protection.

  3. Coordinate Ownership, Entities, and Trusts

    The estate plan should reflect what actually exists. Companies, real estate, ownership interests, trusts, and governing agreements need to be reviewed together so assets are held where the owner believes they are and each structure still serves its intended purpose.

  4. Prepare for Succession and Continuity

    Someone other than the founder may eventually need to understand the structure and make decisions within it. The plan should identify who has authority, how ownership changes, who operates the business, and what a spouse, partner, trustee, or successor should do next.

  5. Plan Before a Sale or Liquidity Event

    A sale, buyout, transfer, or public offering can change the planning analysis quickly. Ownership, trust, and tax strategies should be evaluated early because some opportunities narrow or disappear once the transaction is substantially complete.

  6. Carry the Business Story Into the Family Legacy

    Later-stage planning should help the next generation understand more than the value of the company. It can preserve the history, judgment, expectations, and lessons behind the wealth so future trustees and family members understand what the founder hoped the assets would accomplish.

Planning Across the Business Lifecycle

The company’s needs and the owner’s exposure change over time. Planning should be revisited when the business moves into a new stage rather than remaining frozen around the circumstances that existed when the first documents were signed.

  1. Early Stage

    Build the Foundation

    Create the core estate plan, address incapacity, establish a revocable trust when appropriate, and give your family a workable structure if something happens to you. At this stage, the priority is clear authority and a dependable personal foundation.

  2. Growth Stage

    Manage Increasing Risk

    As your company adds employees, debt, facilities, personal guarantees, and value, review your exposure and the entity structure. Consider whether valuable personal assets remain unnecessarily connected to business risks and whether your existing estate plan still reflects how ownership works.

  3. Maturity and Exit

    Plan Before the Transaction

    When a sale, buyout, transfer, or other liquidity event becomes possible, evaluate the ownership and tax consequences before the deal is complete. The timing of trust, income-tax, gift-tax, and estate-tax planning can materially affect which options remain available.

  4. Legacy Stage

    Prepare the Next Generation

    Organize the structure, clarify succession, and give the family context for the wealth the business created. Future trustees and family members may need to understand why entities exist, how the business should continue, and what values or expectations should guide long-term decisions.

Explore the Planning That Fits Your Situation

Use these broader planning areas to understand where your current concerns fit and which issues may need attention next.

  • Foundational Planning

    Build the core trust, incapacity, and succession structure that gives your family and decision-makers clear authority.

  • Advanced Planning

    Address asset protection, tax opportunities, major transactions, and family objectives that extend beyond foundational documents.

  • Business Planning

    Coordinate ownership, entities, succession, exit decisions, and the business interests that must work with the estate plan.

  • Trust Administration

    Understand what trustees and family members must do when a trust needs to operate after incapacity or death.

Integrated Planning

The Founder Should Not Be the Only Person Who Understands the Structure

Business owners often build complexity one decision at a time. One entity holds real estate. Another owns an operating company. Agreements, financing, trusts, and ownership changes accumulate as the business grows. The founder may understand how everything fits together even when no one else does.

A coordinated plan makes that structure visible. It identifies what exists, verifies how assets and business interests are owned, connects the entities with the estate plan, and clarifies who can act if the owner becomes incapacitated or dies. That process may reveal outdated entities, ownership gaps, or protections that do not work as the owner assumes.

Each layer should still serve a purpose, and a spouse, trustee, business partner, or successor should be able to understand what happens next. When the structure no longer lives only in the founder’s head, the family inherits a usable system instead of an organizational chart without an explanation.

Jeff Cardon reviewing estate planning documents with a client in his Pleasant Grove, Utah office.

Questions Business Owners Often Ask

Make Sure Your Estate Plan Keeps Up

Your business, personal wealth, family responsibilities, and future plans will continue to change. Your estate plan should be able to change with them. Cardon Law can help you identify what needs attention now, coordinate the structures already in place, and build a clearer plan for the people who may eventually have to carry it forward.

Schedule a Consultation